Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
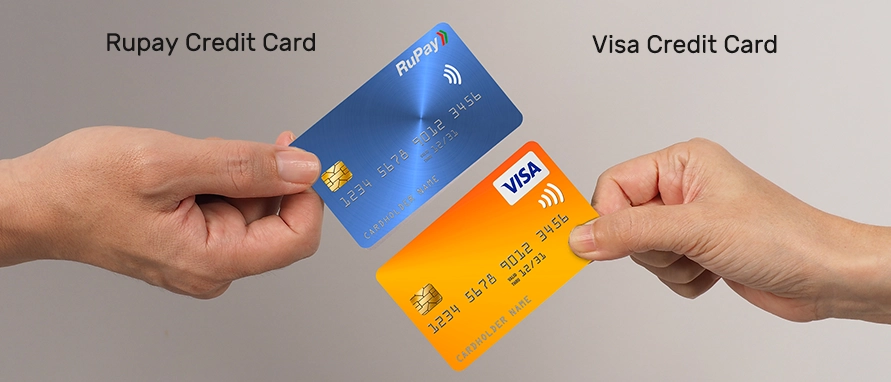
Table of Content
A straightforward comparison of Rupay and Visa credit cards to help you choose the ideal network for your spending style.
Choosing the right credit card network is a critical decision for consumers, as it directly impacts card acceptance, rewards, fees, and access to perks. Rupay and Visa are two prominent networks in India, each with its unique offerings. This article provides a comprehensive comparison of Rupay and Visa credit cards, helping you decide which card best fits your spending habits and lifestyle.
Both RuPay and Visa credit cards offer a range of features tailored to different user needs, catering distinctly to domestic convenience and international accessibility, respectively.
Here’s how they compare across major spending categories:
| Feature | Rupay Credit Card | Visa Credit Card |
|---|---|---|
Shopping |
Good domestic offers |
Extensive global merchant offers |
Dining |
Select local partnerships |
Wide international tie-ups |
Travel |
Limited to Indian partners |
Global travel deals & insurance |
UPI Compatibility |
Full UPI linkage |
Limited UPI support |
Security |
Domestic data storage |
Global security protocols |
Based on the above comparison, Rupay credit cards are ideal if you prioritise domestic spending, prefer UPI integration, and regularly benefit from local merchant deals. On the other hand, Visa credit cards excel in global acceptance, providing extensive international offers, making them particularly suited for frequent travellers and international online shoppers.
Visa is a multinational financial services corporation based in the United States, founded in 1958. It has since grown into one of the most widely used payment networks globally, operating in more than 200 countries and territories.
RuPay is an Indian domestic card scheme launched by the National Payments Corporation of India (NPCI) in 2012, developed to support the Reserve Bank of India's vision of a domestic, open, and multilateral payment system tailored to Indian consumers and merchants.
Choosing between a Rupay credit card and a Visa credit card significantly impacts the rewards you earn. Understanding their respective cashback offers and points structures ensures you maximise benefits based on your spending patterns.
The following table provides a clear comparison of how the credit cards differ. Have a look to get a better understanding of their fee structures, rewards programmes, and criteria for fee waivers:
| Feature | Rupay Credit Card | Visa Credit Card |
|---|---|---|
Joining/Annual Fees |
Typically lower joining and annual fees |
Wide range: zero-fee to premium options |
Fee Waiver Criteria |
Linked to modest annual spending |
Usually linked to higher annual spending |
Rewards & Cashback Focus |
Emphasis on local categories (groceries, fuel, utilities) |
Diverse rewards: travel, merchandise, cashback options |
Understanding the hidden charges is crucial when choosing between Rupay and Visa credit cards. While both networks have transparent terms, certain additional charges could impact your overall spending.
These potential charges are explained clearly in the following points below:
Rupay credit cards generally have fewer hidden charges, making them particularly appealing for users focused on domestic spending. Rupay cardholders can typically avoid additional fees associated with currency conversion and international transactions. Such transparency helps users manage their budgets more effectively, reducing unexpected costs.
Visa credit card users making international purchases or travelling abroad may encounter foreign transaction fees, typically ranging from 1.5% to 3.5% of the purchase amount. Additionally, currency conversion charges may apply, adding to overall transaction costs. Premium Visa cards might also have extra surcharges due to their extensive perks and rewards programmes, making it essential for users to carefully review terms.
Visa credit cards enjoy extensive global acceptance, making them highly suitable for overseas travel and international online purchases. On the other hand, Rupay credit cards are primarily accepted in India and select countries, offering the advantage of direct linkage with UPI apps. This provides seamless and convenient domestic transactions, a feature that remains limited with Visa cards.
This is why comparing fees and charges is vital when deciding between a Rupay credit card and a Visa credit card. The table below outlines the differences, helping you identify the most cost-effective option:
| Fee Type | Rupay Credit Card | Visa Credit Card |
|---|---|---|
Joining Fee |
Low/None |
Varies (₹0 to ₹5,000+) |
Annual Fee |
Low/None |
Varies (₹0 to ₹10,000+) |
Foreign Transaction |
Not supported/inactive |
1.5%–3.5% of transaction value |
UPI Compatibility |
Full integration |
Partial/limited |
Disclaimer: The fees, charges, and waiver conditions mentioned above are indicative and may vary based on the issuing bank, specific card type, and policy updates. For precise and updated fee structures, always refer directly to your issuing bank’s official terms and conditions.
Card acceptance and payment flexibility significantly influence your overall credit card experience. Understanding how Rupay and Visa differ in acceptance and network reach helps you identify the most convenient choice, as detailed below:
Note: If you value travel and lifestyle perks, Visa cards generally offer more comprehensive benefits, including airport lounge access, travel insurance, and exclusive global offers.
Travel perks and additional benefits greatly enhance the value you gain from your credit card. Exploring how Rupay and Visa credit cards differ in terms of travel advantages and extra privileges is essential. Doing so can help you align your card choice effectively with your lifestyle preferences.
Have a look at their individual benefits to get a better understanding:
Domestic airport lounge access (limited to select airports and cards).
Local merchant discounts and government-backed offers.
UPI-enabled for easy domestic payments.
Extensive domestic and international lounge access.
Complimentary travel insurance, concierge services, and global emergency assistance (on premium cards).
Access to exclusive lifestyle and dining programs.
Neither is universally better RuPay suits domestic spending, UPI integration, and lower fees, while Visa suits international travel, global acceptance, and premium travel perks. The right choice depends on your spending pattern and travel habits.
Yes, as per NPCI's current framework, RuPay credit card transactions on UPI up to ₹2,000 do not attract a merchant discount rate (MDR) charge, keeping small transactions free for the cardholder and merchant.
Some banks allow existing cardholders to request a network conversion between RuPay and Visa, subject to the specific card variant and the bank's internal policy. It's best to check directly with your card-issuing bank for available options.
Several banks offer RuPay credit cards with zero or low joining and annual fees, often as part of lifetime-free or entry-level card variants. The exact list of free RuPay cards varies by bank and is worth checking on the issuer's current offer page.
RuPay is owned and operated by the National Payments Corporation of India (NPCI), an Indian entity, making it a domestic card scheme developed specifically for the Indian market.
Most major Indian banks issue RuPay cards, including SBI, HDFC Bank, ICICI Bank, Axis Bank, Punjab National Bank, and Bank of Baroda, among others, across debit, credit, and prepaid card categories.
RuPay may not be accepted at certain international merchants or online platforms because its acceptance network is primarily domestic. This is due to RuPay's more limited global merchant tie-ups compared to established international networks like Visa or Mastercard.

 47201

Navigate the tax maze with ease! Uncover Income Tax 101, demystify jargon with Terms for Beginners, and choose between Old or New Regimes.
 165300
Unlock the world of credit! From picking the perfect card to savvy loan management, navigate wisely.
 97860
Money Management and Financial Planning covers personal finance basics, setting goals, budgeting...
 28591
Explore the investment cosmos! From beginner's guides to sharp-witted strategies, explore India's treasure trove of options.
 18763
Discover essential insights on various types of insurance in India.
 4583
Welcome to Tech in Finance, where we explore the exciting intersection of technology and finance...





 Academy