Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
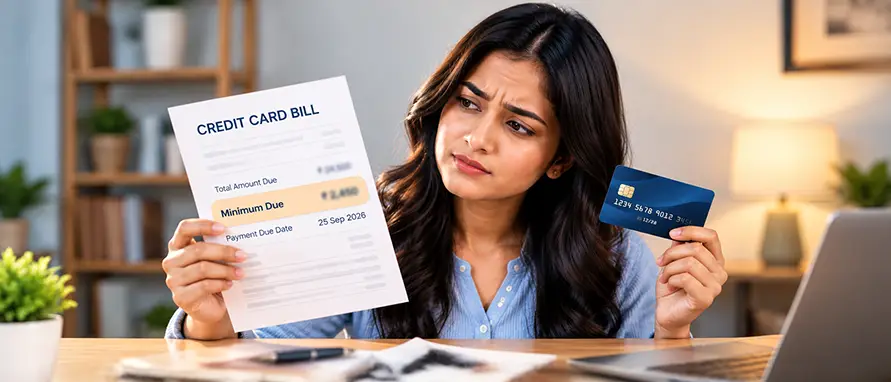
The minimum amount due on an HDFC Bank credit card is the minimum payment you must make by the due date. Paying only this amount helps keep the account active but does not clear your entire credit card bill.
The Minimum Amount Due (MAD) is the minimum amount shown in your HDFC Bank credit card statement that you must pay by the payment due date to keep your card account from becoming overdue. It is calculated by the bank based on various components of your outstanding balance and is displayed separately from the Total Amount Due.
It is important to understand that paying the Minimum Amount Due is not the same as clearing your credit card bill. While paying the MAD can help you avoid late payment charges, the remaining unpaid balance is carried forward, and finance charges may apply on the outstanding amount.
HDFC Bank revised its Minimum Amount Due (MAD) calculation with effect from credit card statements generated from June 2025 onwards. The calculation is no longer based on a simple percentage of the outstanding balance. Instead, it considers multiple components, including retail spends, cash advances, finance charges, EMIs, fees, charges, GST, and any over-limit amount.
If 5% of the finance charge, retail spends, and cash advance balance is higher than the finance charge, the MAD includes:
Total GST
EMI amount
100% of fees and charges
5% of finance charge, retail spends, and cash advance balance
Over-limit amount, if applicable
If 5% of the finance charge, retail spends, and cash advance balance is lower than the finance charge, the MAD includes:
Total GST
EMI amount
100% of fees and charges
100% of finance charges
5% of retail spends and cash advance balance
Over-limit amount, if applicable
Any unpaid MAD from previous statements is added to the current statement's MAD. HDFC Bank also specifies a minimum MAD of ₹200 in certain scenarios.
Example:
Suppose your statement shows retail spends of ₹25,000, an EMI of ₹5,000, finance charges, GST, and applicable fees. In such a case, your Minimum Amount Due will include the full EMI amount, the applicable GST and fees, along with the calculated percentage of the retail balance and finance charges as per HDFC Bank's MAD formula. As a result, the MAD may be significantly higher than a simple 5% of your outstanding amount.
| Parameter | Minimum Amount Due | Total Amount Due |
|---|---|---|
Meaning |
Minimum payment required to keep the account from becoming overdue |
Entire outstanding amount shown in the statement |
Amount Payable |
Only a portion of the outstanding balance |
Full statement balance |
Late Payment Implication |
Paying it helps avoid late payment charges |
Paying it clears the statement balance fully |
Finance Charges |
May apply on the unpaid balance |
No finance charges on statement dues if paid in full by the due date |
Interest-Free Period on New Transactions |
May no longer be available |
Usually continues if the full amount is paid on time |
Outstanding Carried Forward |
Yes, remaining balance is carried forward |
No statement balance is carried forward |
Recommended Payment Approach |
Useful when you cannot pay the full bill |
Generally the preferred repayment option |
A credit card billing cycle is the period between two statement generation dates during which your card transactions are recorded. At the end of each billing cycle, HDFC Bank generates a credit card statement showing your Total Amount Due, Minimum Amount Due (MAD), payment due date, and transaction details.
Understanding your billing cycle is important because the Minimum Amount Due is calculated based on the transactions, EMIs, charges, and outstanding balances reflected in that statement. It also helps you plan repayments and avoid finance charges by paying your dues before the due date.
Even if you are unable to pay the entire outstanding amount, paying at least the Minimum Amount Due can help keep your credit card account in good standing.
Paying the Minimum Amount Due by the due date can help you avoid late payment fees.
It ensures that your account is not treated as overdue for that billing cycle.
Making at least the minimum payment demonstrates repayment discipline.
A consistent repayment record can support a healthier credit profile over time.
Missing even the Minimum Amount Due may lead to additional charges and account delinquencies.
Timely payment helps keep your credit card account active and compliant with the card terms and conditions.
Paying your credit card dues on time can help you avoid late payment charges, maintain a healthy repayment record, and reduce the risk of additional costs associated with missed payments.
Create calendar reminders a few days before the payment due date.
Use alerts through your mobile phone, email, or banking app to ensure you do not miss a payment.
Set up automatic payments from your savings or current account.
This helps ensure that at least the Minimum Amount Due or the outstanding bill amount is paid on time.
Register for auto-debit or Electronic Clearing Service (ECS) facilities offered by the bank.
These options can help automate repayments and reduce the chances of missing the due date.
Review your transactions and outstanding balance regularly through NetBanking, mobile banking, or your monthly statement.
Monitoring your spending can help you plan repayments better and avoid payment-related issues.
No. HDFC Bank revised its Minimum Amount Due (MAD) calculation from the June 2025 statement onwards. The MAD is calculated using components such as retail spends, cash advances, finance charges, EMIs, fees, charges, GST, and any over-limit amount, rather than a simple 5% of the outstanding balance.
Paying only the Minimum Amount Due can help you avoid late payment charges. However, finance charges may apply on the unpaid outstanding balance, and the remaining amount will be carried forward to the next billing cycle.
You can check the Minimum Amount Due in your monthly credit card statement. It is usually displayed separately from the Total Amount Due and is also available through HDFC Bank's digital banking channels.
You can pay the Minimum Amount Due through various payment methods offered by HDFC Bank, including:
NetBanking
Mobile Banking
Auto-debit facility
UPI-supported payment options
NEFT or other eligible payment channels
The payment must be completed on or before the due date to avoid overdue status.
If you pay only the Minimum Amount Due, your account generally remains in good standing and late payment charges may be avoided. However, the unpaid balance is carried forward to the next statement, and finance charges may be levied on the outstanding amount.
Yes. Even if you pay the Minimum Amount Due, finance charges may be charged on the unpaid outstanding balance. In addition, you may lose the benefit of the interest-free period on new transactions until the dues are cleared as per the applicable terms and conditions.
Yes. You can pay any amount between the Minimum Amount Due and the Total Amount Due, or clear the entire outstanding balance. Paying the Total Amount Due is generally the most effective way to avoid finance charges and maintain the interest-free credit period.

Academy by Bajaj Markets
 47202

Navigate the tax maze with ease! Uncover Income Tax 101, demystify jargon with Terms for Beginners, and choose between Old or New Regimes.
 165541
Unlock the world of credit! From picking the perfect card to savvy loan management, navigate wisely.
 97880
Money Management and Financial Planning covers personal finance basics, setting goals, budgeting...
 28605
Explore the investment cosmos! From beginner's guides to sharp-witted strategies, explore India's treasure trove of options.
 18764
Discover essential insights on various types of insurance in India.
 4584
Welcome to Tech in Finance, where we explore the exciting intersection of technology and finance...




 Academy