Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
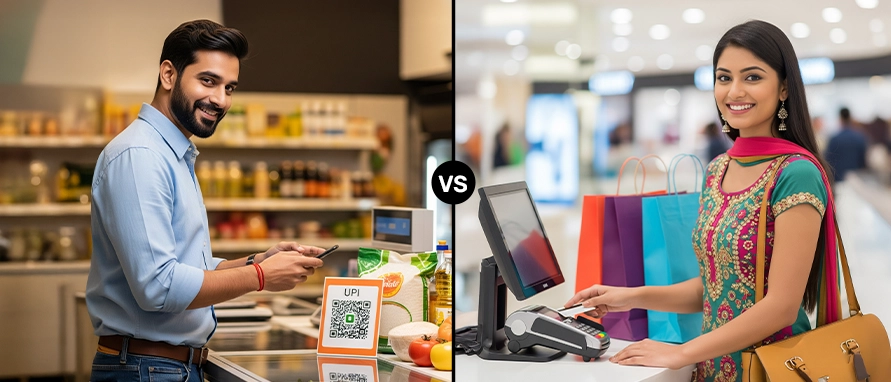
Table of Content
A quick comparison of UPI and traditional card swipes for maximising credit card rewards.
Credit cards have long been favoured for their reward programmes, offering cashback, points, and exclusive deals. However, the arrival of UPI on credit cards has changed the way people pay. This article explores whether UPI payment via credit card or the traditional swipe method is better for maximising your rewards.
UPI payments via credit card allow you to link your credit card to a UPI app. This means you can pay directly from your credit limit, rather than your bank account. Most major UPI apps, such as PhonePe and Google Pay, now let you connect select credit cards, primarily those on the RuPay network.
The process is straightforward. You add your credit card in the UPI app, set a UPI PIN, and can then make payments at any merchant accepting UPI. This method combines the flexibility of credit with the convenience of UPI. It is especially useful for small daily purchases at local shops, where UPI is widely accepted.
The various benefits include:
No need to carry your physical card
Instant transactions, even at small merchants
Access to your credit card’s billing cycle, giving you more time to pay.
Potential to earn reward points or cashback on every UPI payment, if your card supports it.
However, it is important to check your bank’s policy. Some banks may cap rewards for UPI payments or exclude certain categories, such as rent or wallet loads, from earning points.
Traditional swipe payments involve using your physical credit card at a merchant’s point-of-sale (POS) terminal. You swipe, insert, or tap your card, and the transaction is processed through the card network.
Each swipe earns you reward points, cashback, or air miles, depending on your card’s reward structure. Banks and card issuers often partner with merchants to offer bonus rewards on categories like dining, travel, or shopping.
The swipe method is well-established and accepted at most retail outlets, restaurants, and service providers. Rewards are generally consistent, with clear terms on how points are earned and redeemed.
How rewards are earned:
A portion of the merchant fee is shared with the card issuer, who then passes some of it back to you as reward points.
Points can be redeemed for vouchers, merchandise, or statement credit.
Many cards offer milestone bonuses for reaching spending thresholds.
While retailers pay swipe fees directly, they might have an indirect impact on customers. Here's how swipe charges can affect what you pay:
| Aspect | Impact on Customers |
|---|---|
Merchant Pricing |
Some merchants may build swipe costs into product or service prices |
Cash vs Card |
Cash payments sometimes avoid this indirect cost, since no swipe fee applies |
Online Payments |
Often cheaper to process, which can mean lower swipe costs passed on |
Fee Transparency |
RBI oversight helps ensure swipe charges remain fair and disclosed |
Online credit card payments are convenient and may have lower swipe costs than physical POS transactions due to lower interchange rates. Knowing these charges can help you choose between credit, cash, or online payment methods.
Credit card swipe charges, also known as interchange fees, are generally paid by retailers rather than customers directly. When a merchant accepts a swipe payment through a POS terminal, they pay a percentage of the transaction (typically around 2%) to the card-issuing bank as a fee for using the payment infrastructure. The Reserve Bank of India (RBI) oversees these charges to ensure fairness and transparency across the payment ecosystem. In rare cases, issuing banks may levy additional charges, though this is uncommon for standard consumer transactions.
Both UPI payment via credit card and traditional swipe offer rewards, but there are differences in how much you can earn and where you can use each method. Here’s a closer look:
| Feature | UPI on Credit Card | Traditional Swipe |
|---|---|---|
Merchant Acceptance |
Widely accepted, even at small shops |
Accepted at most retail outlets |
Reward Points |
Earned, but may be capped or limited |
Earned on almost all purchases |
Convenience |
No need to carry card, instant |
Physical card needed |
Eligible Card Networks |
Mostly RuPay |
Visa, MasterCard, RuPay |
Exclusions (No Rewards) |
Some categories excluded |
Fewer exclusions |
Billing Cycle |
Yes |
Yes |
Disclaimer: The comparison above is indicative. Actual rewards, acceptance, and terms may vary based on your credit card issuer, merchant, and applicable regulations. Always confirm with your card provider.
UPI payments via credit cards combine digital convenience with reward benefits, making transactions swift and cash-free. However, it's essential to weigh both advantages and potential drawbacks before choosing this payment mode. Here's a quick overview:
| Pros | Cons |
|---|---|
Convenient, card-free payments |
Limited to select RuPay credit cards |
Accepted widely at small merchants and QR-only outlets |
Possible reward caps or category restrictions |
Billing cycle and credit benefits remain intact |
Not accepted at merchants without QR payment options |
Earns equal rewards as traditional swipes (RuPay cards) |
Ease of payments may encourage overspending |
Traditional swipe payments using credit cards are reliable and universally accepted, offering extensive reward opportunities. Yet, carrying a physical card has its limitations and risks. Here’s a closer look at the key points:
| Pros | Cons |
|---|---|
Widely accepted across retail stores, hotels, restaurants |
Must carry the physical credit card at all times |
Reliable and consistent rewards for most purchases |
Less convenient at small merchants or street vendors |
Access to bonus categories and milestone rewards |
Some merchants impose minimum transaction limits |
Extensive choice of card networks and reward programmes |
Risk of physical card being lost, stolen, or skimmed |
Here's how to link and use your credit card for UPI payments:
1. Open a UPI app that supports credit card linking.
2. Navigate to the option to add a credit card or bank account.
3. Select your card issuer and enter your RuPay credit card details.
4. Verify the card using the OTP sent to your registered mobile number.
5. Set a UPI PIN for the linked card.
6. Once linked, scan a QR code or enter a UPI ID to make payments directly from your credit limit.
Choosing the optimal payment method depends significantly on your spending habits and preferences. Understanding your usage patterns will help maximise the benefits from your credit card rewards.
Consider these guidelines to select the right approach:
If you shop frequently at local stores or prefer cashless convenience, UPI on credit card can be very rewarding, provided your card offers points on UPI spends.
For high-value purchases, travel, or shopping at large retailers, traditional swipe payments are more reliable for earning consistent rewards.
Some users combine both methods: using UPI for daily essentials and swiping for larger expenses, maximising rewards across categories.
Always review your card’s reward policy. Some cards may offer better rates for swipes, while others treat UPI and swipe equally.
Yes, most RuPay credit cards offer reward points on UPI transactions, but some banks may cap or exclude certain spends.
Currently, only selected RuPay credit cards can be linked to UPI apps for direct payments.
Not always. Some cards offer equal rewards, while others limit points on UPI spends. Check your card’s terms.
Yes, UPI payments via credit card use secure authentication and PIN verification, making them safe for everyday use.
If your card offers full rewards on both, use UPI for small spends and swipe for bigger purchases. Otherwise, traditional swipe is more reliable for consistent rewards.

 47201

Navigate the tax maze with ease! Uncover Income Tax 101, demystify jargon with Terms for Beginners, and choose between Old or New Regimes.
 165300
Unlock the world of credit! From picking the perfect card to savvy loan management, navigate wisely.
 97860
Money Management and Financial Planning covers personal finance basics, setting goals, budgeting...
 28591
Explore the investment cosmos! From beginner's guides to sharp-witted strategies, explore India's treasure trove of options.
 18763
Discover essential insights on various types of insurance in India.
 4583
Welcome to Tech in Finance, where we explore the exciting intersection of technology and finance...





 Academy