Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
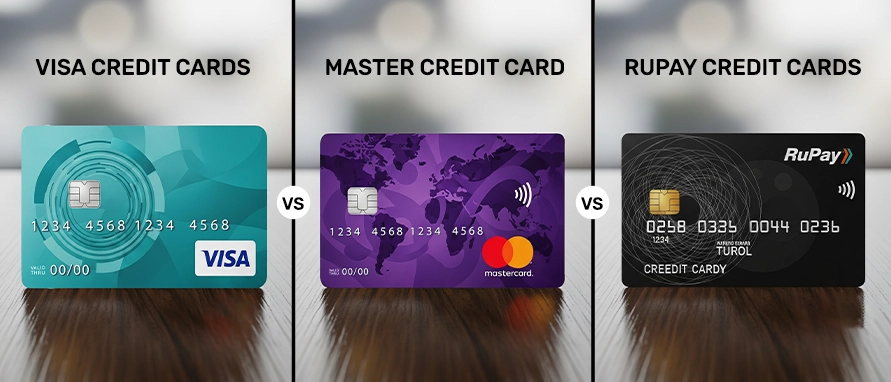
Table of Content
Compare credit cards from Visa, Mastercard, and RuPay to help you decide which card network and its features matches your spending habits, travel needs, and reward preferences.
Credit cards have changed the way Indians handle payments, offering convenience, rewards, and safety. Choosing the right network RuPay credit card, Visa credit card, or Mastercard credit card can affect your spending, rewards, and international acceptance. This article helps you compare these networks for Indian users, so you can make an informed choice based on your lifestyle and needs.
There's no single 'best' network RuPay suits domestic, UPI-linked spending with lower costs, while Visa and Mastercard suit international travel and premium global acceptance. Here's a quick snapshot before the detailed comparison below:
| Aspect | RuPay | Visa | Mastercard |
|---|---|---|---|
Ownership |
NPCI (India) |
Visa Inc. (USA) |
Mastercard Inc. (USA) |
Acceptance |
India-first, growing international footprint via UPI and select partnerships |
200+ countries |
200+ countries |
UPI Linkage |
Native UPI integration |
Not UPI-linked |
Not UPI-linked |
Typical Forex Markup |
Lower on UPI-based cross-border payments; standard network markup applies for RuPay Global cards used abroad |
1.5%–3.5% (issuer-set, verify with your bank) |
1.5%–3.5% (issuer-set, verify with your bank) |
A credit card actually involves two separate parties: the network and the issuing bank. The card network (Visa, Mastercard, or RuPay) provides the payment rails the infrastructure that processes your transaction and determines where the card is accepted, its base security standards, and cross-border transaction handling.
The issuing bank (such as HDFC, ICICI, SBI, or Axis) is the entity that actually gives you the card, sets your credit limit, decides the interest rate, and designs the rewards, cashback, and fee structure. Two cards on the same network say, two different Visa cards can have completely different rewards and charges, because those are set by the issuing bank, not by Visa itself.
QR code and pay directly from your credit limit instead of your bank account balance.
This works at any UPI-enabled merchant across India, from small local shops to large retailers, since it uses the same UPI infrastructure as regular bank-linked UPI payments. Some banks also extend this to RuPay credit cards used through UPI apps in the small number of countries where UPI is now live for cross-border payments, including Singapore, the UAE, France, Sri Lanka, Mauritius, Bhutan, Nepal, Qatar, and Cambodia, though acceptance depends on your specific bank and UPI app enabling this feature.
This linkage is one of RuPay's clearest advantages over Visa and Mastercard credit cards, neither of which currently supports UPI-based payments.
When comparing these three networks, it is important to look at ownership, reach, security, welcome benefits, annual charges, eligibility, and key offers. Each network partners with banks to provide unique card options.
| Parameter | RuPay Credit Card | Visa Credit Card | Mastercard Credit Card |
|---|---|---|---|
Network Ownership |
Owned by NPCI, a domestic Indian entity |
Owned by Visa Inc., a US-based global network |
Owned by Mastercard Inc., a US-based global network |
Reach |
Primarily domestic; growing acceptance abroad via UPI-linked payments and partner networks |
Global accepted in over 200 countries |
Global accepted in over 200 countries |
Security Features |
EMV chip, tokenisation for UPI transactions, 2FA on UPI payments |
EMV chip, Visa tokenisation, Visa Secure (3D Secure) authentication |
EMV chip, Mastercard tokenisation, Identity Check (3D Secure) authentication |
Welcome Benefits |
May include reward points, discounts on select spends, and first-year fee waivers |
May offer cashback, bonus points, or exclusive partner discounts |
Might provide joining bonuses, travel vouchers, or shopping offers |
Annual Charges |
Often lower or zero for entry-level cards; some premium cards have charges |
Varies by card; can be nil (Amazon Pay ICICI) to ₹4,999 (SBI ELITE) |
Ranges from zero to ₹3,000+ for premium cards |
Eligibility |
Indian residents, NRIs; age 18-70; income as per bank policy |
Indian citizens, salaried/self-employed; age 18+; income as per card |
Indian citizens, salaried/self-employed; age 18+; income as per card |
Key Offers |
UPI payments, domestic lounge access, exclusive Indian merchant deals |
Global acceptance, travel deals, insurance, concierge |
International usage, travel and lifestyle perks, mobile insurance |
Examples |
ICICI Coral RuPay, Axis Bank NEO RuPay |
HDFC Moneyback, Amazon Pay ICICI, Axis Flipkart |
Airtel Axis Bank Mastercard, SBI Mastercard SELECT |
Note: Banks may update benefits and eligibility, so always check the official website before applying.
Credit card rewards can make everyday spending more rewarding. The earning potential varies by network and card type. Here's a breakdown across popular categories:
A RuPay credit card may offer reward points on every purchase, especially when used with UPI for online or offline shopping. For example, ICICI Bank RuPay Credit Cards allow you to earn points on groceries, e-commerce, and utility payments. Visa credit card options like the Axis Flipkart Credit Card offer cashback on e-commerce sites. Mastercard credit card holders might get bonus points at select online retailers.
Many RuPay credit cards provide discounts at partner restaurants and reward points for dining expenses. Visa and Mastercard both offer dining privileges, such as 'Visa Dining Offers' or Mastercard's 'Priceless Cities' experiences, which might include discounts or complimentary dishes at select outlets.
Premium RuPay credit cards like ICICI Coral offer complimentary railway or airport lounge access within India. Visa credit card and Mastercard credit card variants may provide international lounge access, travel insurance, and flight booking discounts. For instance, the SBI ELITE Visa card offers free lounge visits and travel deals, while Mastercard SELECT cards come with trip planning and insurance.
On UPI-linked spending specifically, RuPay credit card on UPI transactions may earn cashback or reward points depending on the issuing bank's policy some banks reward UPI spends at the same rate as regular swipes, while others apply a reduced rate, so it's worth checking your specific card's terms.
Example: A frequent online shopper using the Amazon Pay ICICI Visa Credit Card can earn cashback on Amazon spends, while a domestic traveller may benefit more from a RuPay credit card with UPI integration and railway lounge access.
Disclaimer: The benefits of the respective credit cards mentioned above are added with reference to the information available at the time of writing. For the latest updates, please visit the official website.
Credit card fees and charges can impact your overall benefits. Here’s a comparison of popular cards:
| Card Name | Joining/Annual Fees | Waiver Criteria | Other Charges |
|---|---|---|---|
₹500/₹500 |
Spend ₹1.5 Lakhs/year |
Finance charges, late fee |
|
Axis Bank NEO RuPay Credit Card |
Nil (1st year)/₹250 |
Spend ₹25,000/year |
Cash advance, GST |
Amazon Pay ICICI Visa Credit Card |
Nil (lifetime-free) |
NA |
Foreign markup, late fee |
HDFC Moneyback+ Visa Credit Card |
₹500/₹500 |
Spend ₹50,000/year |
Reward redemption fee |
Airtel Axis Bank Mastercard Credit Card |
₹500/₹500 |
Spend ₹2 Lakhs/year |
EMI charges, late fee |
SBI ELITE Visa Credit Card |
₹4,999/₹4,999 |
Spend ₹10 Lakhs/year |
High annual fee, foreign markup |
Banks may waive annual fees if you meet the spend criteria. Always check for hidden charges like cash withdrawal fees, foreign currency markup, and late payment penalties on the official card website.
Disclaimer: The benefits of the respective credit cards mentioned above are added with reference to the information available at the time of writing. For the latest updates, please visit the official website.
Acceptance and payment flexibility are crucial for Indian users.
A RuPay credit card is accepted at almost all Indian ATMs, POS, and e-commerce sites. It is ideal for domestic transactions and offers seamless UPI integration, letting you pay at UPI-enabled merchants using your credit card.
RuPay's international reach comes through two separate routes: RuPay Global or RuPay Select cards, which use partnerships with networks like Discover and JCB for card-present acceptance abroad, and UPI-linked payments, now live in 9 countries as of 2026 Singapore, the UAE, Bhutan, Nepal, Sri Lanka, France, Mauritius, Qatar, and Cambodia. These are two distinct mechanisms, and acceptance depends on which one your specific card and bank support.
Visa credit cards and Mastercard credit cards are accepted worldwide, making them suitable for international travellers and online shoppers. Both networks support contactless payments, global ATMs, and advanced security features like tokenisation and zero liability policies.
Example: If you travel abroad or shop on international websites, a Visa credit card or Mastercard credit card might be more useful. For local shopping, UPI payments, and Indian rewards, a RuPay credit card offers unmatched flexibility.
Many credit cards provide travel and lifestyle perks:
Example: A frequent flyer may benefit from the SBI ELITE Visa card for international lounge access, while a domestic traveller might prefer the ICICI Coral RuPay credit card for railway and airport lounge perks.
Disclaimer: The benefits of the respective credit cards mentioned above are added with reference to the information available at the time of writing. For the latest updates, please visit the official website.
Choosing the right card depends on your lifestyle and spending habits.
Choosing between a RuPay credit card, a Visa credit card, and a Mastercard credit card depends on your needs. If you want domestic rewards and UPI payments, RuPay might suit you. For international use and premium perks, Visa or Mastercard could be better. Remember that most rewards, fees, and perks are set by your issuing bank, not the network so compare specific cards, not just networks, before applying.
Yes, eligible RuPay Global and RuPay Select cards can be used internationally. RuPay credit cards linked to UPI can also support QR payments in selected countries, subject to bank and UPI app support.
Neither is clearly better. Both offer similar global acceptance and security. The real difference comes from the specific card and bank you choose.
Sometimes. Some banks let you pick Visa, Mastercard, or RuPay for the same card. Others issue only one network. Check with your bank.
No. Rewards and cashback are set by the issuing bank, not the network. Two cards on the same network can have very different reward rates.
Yes. You can link a RuPay credit card to apps like Google Pay or PhonePe and pay via UPI.

Most Viewed
 47201

Navigate the tax maze with ease! Uncover Income Tax 101, demystify jargon with Terms for Beginners, and choose between Old or New Regimes.
 165300
Unlock the world of credit! From picking the perfect card to savvy loan management, navigate wisely.
 97860
Money Management and Financial Planning covers personal finance basics, setting goals, budgeting...
 28591
Explore the investment cosmos! From beginner's guides to sharp-witted strategies, explore India's treasure trove of options.
 18763
Discover essential insights on various types of insurance in India.
 4583
Welcome to Tech in Finance, where we explore the exciting intersection of technology and finance...





 Academy