Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
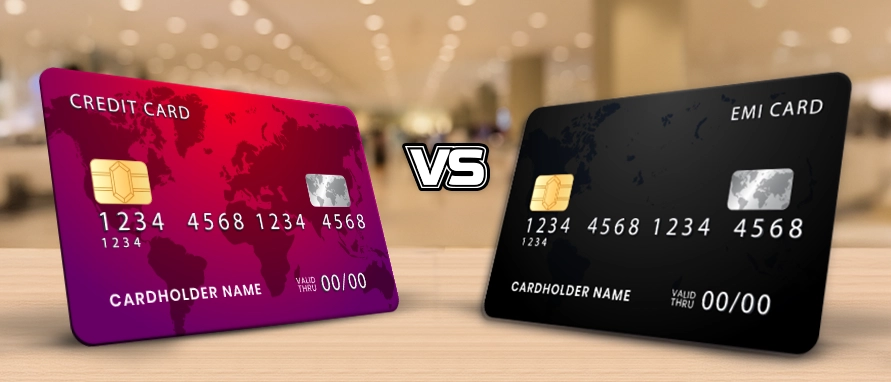
Table of Contents
From the moment salaries are credited into accounts, their fates are doomed. They say, “the heart wants what it wants,” which couldn’t be more accurate. The credited amount is split within a short period between recurring payments like EMIs, utility bills, salaries, etc. But that’s not all. By the time pay-day arrives, wishlists are overflowing with different desires. The heart continues to covet until the next paycheck arrives – even if the bank account is running on fumes!
So, what do you do? Between numerous financial obligations, like paying off the essentials, there’s little to no room left for the occasional indulgence. While scouring the internet for viable solutions, you might come across different companies offering lucrative deals on credit cards or EMI cards. If you don’t already own one of these, choosing between the two might throw you off.
Before applying for a credit card or EMI card, learn more about these payment options and their features.
Credit cards and EMI cards both give cardholders instant access to pre-approved funds, which is often where the confusion between the two begins. In practice, though, they serve different purposes and cater to different spending needs. Here's a side-by-side look at the key differences:
| Point of Comparison | Credit Card | EMI Card |
|---|---|---|
Meaning |
A revolving credit instrument that lets you make purchases now and repay later, in full or via EMI conversion |
A pre-approved credit limit dedicated to converting purchases into instalments at the time of buying |
Interest Charges |
Interest applies on outstanding dues not paid in full by the due date; EMI conversions may or may not carry interest depending on the offer |
Many EMI cards offer Easy EMI options, so interest may not apply, depending on the card and merchant |
Rewards & Benefits |
Offers cashback, reward points, joining gifts, airport lounge access, and category-specific perks |
Primarily focused on facilitating EMI purchases, with typically fewer lifestyle rewards |
Repayment Flexibility |
Full repayment, partial repayment, or EMI conversion are all available, though partial repayment attracts interest on the remaining balance |
Repayment is structured as fixed EMIs over a chosen tenure, from the time of purchase |
Foreclosure |
Prepayment or foreclosure charges may apply, depending on the issuer and terms |
Many EMI cards allow foreclosure of outstanding dues without penalty |
Usage Scope |
Widely accepted for various types of purchases, bill payments, and online transactions |
Typically used for converting specific purchases into instalments, both online and offline |
Best Suited For |
Individuals who want rewards, cashback, and broader spending flexibility |
Individuals who want a structured, instalment-based way to finance specific purchases |
Credit cards and EMI cards offer users the benefit of purchasing items by converting the transaction into an EMI. However, that doesn’t necessarily make one better than the other! Based on your financial requirements or lifestyle, opt for the one that aligns with your interest.
For better clarity on the matter, let’s explore both the options for the different payment experiences they offer.
The best way to determine which card type suits you best is to narrow down the different expenses they will be used to finance. Do you want a card for uninterrupted shopping sprees? Or, perhaps, you’re a connoisseur of good food and times? Based on your answers to those questions, choose between a credit card or an EMI card.
That said, another factor to consider is the payment experience. While both the cards offer the EMI option, they come with their terms and conditions. Let’s understand how they both work via the following two examples.
Example #1: Converting e-commerce transactions into credit card EMIs
Merchant EMI offers, available at stores and online portals, are based on tie-ups between manufacturers and credit card companies. Through this arrangement, interest rates are pre-determined without much consideration to whom they’re offered. Usually, customers are subject to the same interest rates without many exceptions.
The processing fees and interest rates are charged against the online price in this case. Based on this, customers can either convert the payment into affordable EMIs or complete the repayment during the next billing cycle.
Example #2: Converting payments into EMIs during the purchase
Unlike the previous option, EMI cards solely allow payments on an instalment basis. However, it gives users the flexibility to choose between short-and-long-term tenures. Depending on the feasibility of these tenures, cardholders can complete the purchase and repay the amount over a preferred tenure.
Certain EMI cards also offer customers no-cost EMIs that don’t impose any interest rate on the amount used.
The next time a situation arises that requires you to decide between credit cards or EMI cards, think carefully! While they serve similar purposes of providing access to funds, they couldn’t be more different. Credit cards are a lucrative option for individuals who want additional benefits like rewards, cash backs, and other bonus points. In contrast, EMI cards are a great alternative to credit cards if you plan to limit their use to financing purchases.
Whether you’re on team credit cards or team EMI cards, we have a simple solution for you. Visit Bajaj Markets and find out which of the two works best for you – apply for credit cards or an EMI card today!
A credit card is general-purpose ""plastic money"" offering rewards, interest-free periods, and EMI conversion. An EMI card only lets you buy products on instalments at partner stores, with no direct spending or rewards.
Neither is universally better. Choose a credit card for rewards, cashback, and flexible spending; choose an EMI card if you mainly want to finance purchases through instalments.
Yes. Credit cards let you convert transactions into EMIs through merchant offers or your billing cycle, with pre-determined interest rates and processing fees on the online price.
Not always. Certain EMI cards offer no-cost EMIs with zero interest on the amount used, and let you foreclose outstanding dues without penalty fees.
Yes. They serve different purposes, so many people use a credit card for everyday spending and rewards while keeping an EMI card for financing bigger purchases.

Most Viewed
Academy by Bajaj Markets
 47201

Navigate the tax maze with ease! Uncover Income Tax 101, demystify jargon with Terms for Beginners, and choose between Old or New Regimes.
 165300
Unlock the world of credit! From picking the perfect card to savvy loan management, navigate wisely.
 97860
Money Management and Financial Planning covers personal finance basics, setting goals, budgeting...
 28591
Explore the investment cosmos! From beginner's guides to sharp-witted strategies, explore India's treasure trove of options.
 18763
Discover essential insights on various types of insurance in India.
 4583
Welcome to Tech in Finance, where we explore the exciting intersection of technology and finance...





 Academy