Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
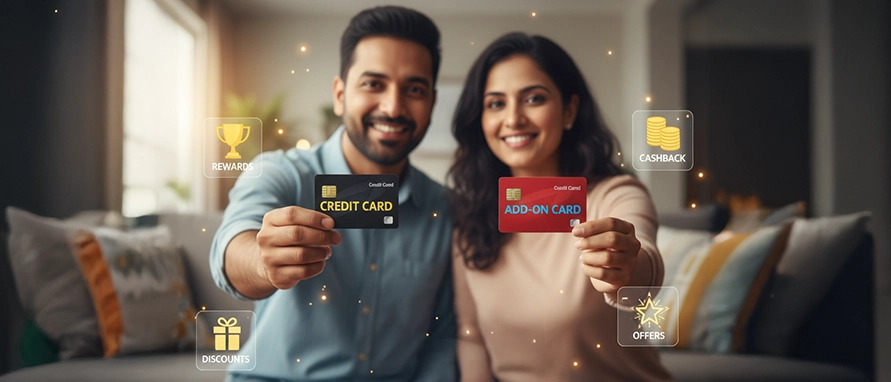
Top credit cards with add-on card benefits let you share one limit with family members, keeping control over your spending. An add-on credit card allows easier tracking by setting usage caps. This page explains key add-on credit card benefits It also lists things you must check before applying to help you choose the best add-on credit card for you.
You can find add-on credit card options on Bajaj Markets for 2026. These cards offer add-on credit card benefits like shared credit limits and family usage. Primary cardholders can control spending and manage multiple cards easily.
Credit Cards |
Main Benefits |
Number of Add-ons Allowed |
Best Use Cases |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
You can compare different add-on credit card features before choosing one. Each card offers different credit limits, rewards, and fee structures for add-on cards.
Credit Card |
Reward Sharing |
Annual Fee for Add-ons |
Reward Earning on Add-on Spends |
Tata Neu Plus HDFC Bank Credit Card |
NeuCoins earn into the primary account |
Nil (Lifetime Free) |
Earns 2% NeuCoins on Tata Neu/Partners, 1% on others (credited to primary) |
SimplySAVE SBI Card |
Rewards accumulate in primary account |
Nil |
Earns 10X Reward Points on Dining, Movies, Grocery, Departmental Stores |
SBI Card PRIME |
Rewards accumulate in primary account |
Nil |
Earns 20 Reward Points per ₹100 on dining, groceries, movies |
SimplyCLICK SBI Card |
Rewards accumulate in primary account |
Nil |
Earns 10X Reward Points on exclusive online partners; 5X on other online spends |
SBI Card ELITE |
Rewards accumulate in primary account |
Nil |
Earns 5X Reward Points on Dining, Departmental Stores, Grocery |
BPCL SBI Card |
Rewards accumulate in primary account |
Nil |
Earns 13X Reward Points on fuel purchases at BPCL pumps |
IRCTC Rupay SBI Card |
Rewards accumulate in primary account |
Nil |
Earns up to 10% Value Back as Reward Points on AC1/AC2/AC3 bookings on IRCTC |
SBI Card OCTANE |
Rewards accumulate in primary account |
Nil |
Earns 25X Reward Points on fuel purchases at BPCL pumps |
SBI Card PULSE |
Rewards accumulate in primary account |
Nil |
Earns 10 Reward Points per ₹100 on Chemist, Pharmacy, Dining, Movies |
IDFC FIRST Bank Millennia Credit Card |
Rewards accrue to primary account |
Nil (Note: Recent updates may apply fees for new issuances; check current MITC) |
Earns 10X Reward Points on incremental spends >₹20k & birthday spends |
IDFC FIRST Bank CLASSIC Credit Card |
Rewards accrue to primary account |
Nil (Note: Recent updates may apply fees for new issuances; check current MITC) |
Earns 10X Reward Points on incremental spends >₹20k & birthday spends |
IDFC FIRST Bank Wealth Credit Card |
Rewards accrue to primary account |
Nil |
Earns accelerated rewards on online/offline spends (points never expire) |
IDFC FIRST Bank Power Credit Card |
Rewards accrue to primary account |
Nil (Note: Power+ variant may carry a ₹499 fee; check specific card terms) |
Earns accelerated rewards on HPCL fuel, grocery, and utility spends |
IDFC FIRST Bank Select Credit Card |
Rewards accrue to primary account |
Nil. |
Earns 10X Reward Points on incremental spends >₹25k & birthday spends |
Indian Oil Kotak Credit Card |
Rewards credited to primary account |
Nil |
Earns up to 4% as Reward Points on Indian Oil fuel spends (pooled with primary) |
Kotak League Platinum Card |
Rewards credited to primary account |
Nil |
Earns 8X Reward Points on select categories; spends help reach annual milestones |
An add-on credit card (or supplementary card) is a secondary card issued against your primary credit card account. It allows you to share your credit limit with immediate family members, such as your spouse, parents, or adult children (usually over 18 years).
How It Works:
Add-on credit card benefits extend beyond just extra cards for family members. You get shared rewards, simplified tracking, and better control over household spending patterns.
Add-on credit cards let family members make purchases without needing separate credit cards
The shared credit limit helps you manage household spending from one account
All transactions appear in one statement. You can monitor and control family expenses easily
Joint spending becomes simpler to track. This helps with budgeting and financial planning for your household.
Many add-on cards credit rewards from add-on spends to the primary card. This boosts overall rewards for the family.
You can manage expenses for dependents through add-on cards. These work well for groceries, travel, or education costs.
Some cards offer additional perks like add-on card lounge access or insurance coverage. Primary and add-on cardholders can share these benefits.
An add-on credit card is issued against an existing primary credit card, so you first need an active primary card. If you don't have one yet, you can apply for credit card options from leading banks and NBFCs on Bajaj Markets, and then request add-on cards for your family members.
Steps to apply for a primary credit card on Bajaj Markets:
Visit the Bajaj Markets credit card page and click on 'Apply Now'
Enter your mobile number and verify it with the OTP sent to you
Fill in basic details such as your name, date of birth, PAN, PIN code and monthly income
Compare the credit card offers you are eligible for and choose the one that suits your needs
Submit your application and complete the remaining process, including KYC, on the card issuer's platform
Steps to request an add-on card on your primary card:
Log in to your card issuer's net banking portal or mobile app, or contact customer care
Go to the credit card services section and select the option to request an add-on card
Enter the add-on applicant's details, such as name, date of birth and relationship with you
Upload the add-on applicant's KYC documents, like an ID proof, address proof and photograph, if required
Set a spending limit for the add-on card, if your issuer allows it, and submit the request
Once approved, the add-on card is delivered to the registered address. All transactions made on it are billed to your primary card account, and they share the same credit limit.
You can use add-on credit cards in various everyday situations. These cards help manage family needs, business expenses, and emergency spending efficiently.
Family travel becomes simpler with add-on cards. Each member can make bookings and purchases using the shared limit. All expenses appear in one statement for easy tracking.
Business owners can give add-on cards to trusted employees. Employees can make work-related purchases while you control and monitor all spending.
You can manage shared household expenses like groceries, utilities, or medical bills efficiently. Give add-on cards to family members for simplified budgeting and tracking.
Elderly parents or relatives benefit from add-on credit card options. You can manage their essential expenses and monitor transactions for financial safety.
Students can use add-on cards for education, shopping, and daily needs. You retain control over spending limits and track usage for better financial discipline.
Add-on cards help manage expenses during emergencies. Dependants get quick access to funds without needing a separate credit application process.
Rewards from add-on credit cards accumulate in the primary cardholder's account. You earn points or cashback from all card transactions made by family members.
All spending made on an add-on credit card earns rewards like points or cashback. These rewards get credited to your primary cardholder account automatically.
Rewards pool into your primary account. You accumulate all points from both primary and add-on card transactions together.
You redeem rewards through your primary cardholder account. Add-on cardholders cannot redeem rewards independently on their own.
Some cards may have specific terms for pooling rewards. Most banks pool all points together for easier redemption and tracking.
Other benefits, like add-on card lounge access or insurance coverage, are generally shared. You control their usage as the primary cardholder.
You must understand certain rules before issuing an add-on credit card. These limitations affect credit limits, liability, and control over spending for all cardholders.
The add-on credit card shares your primary card's credit limit. Combined spends of both cards must stay within this total limit.
You remain fully liable for all transactions made on the add-on card. This includes any purchases or payments made by the add-on cardholder.
Card control features let you set spending caps or block the add-on card. You can access these controls through your online banking portal easily.
You can set spending caps for add-on cards to manage usage. This helps control family or employee expenses and prevents overspending effectively.
You can request to close or deactivate the add-on card anytime. This gives you full control over who can use your credit facility.
All transactions made on the add-on card appear on your monthly statement. This allows easy tracking of all household or business expenses together.
You should evaluate several factors before selecting the best add-on credit card. Compare features like card limits, security options, and shared benefits for better value.
Check how many add-on cards the issuer allows. Most banks permit up to 3 add-on cards for immediate family members only.
Look for cards that provide separate PINs for add-on cards. This ensures secure and independent usage for each cardholder in your family.
Confirm if rewards and points from add-on card spends pool into your account. This helps maximise overall rewards for your entire family efficiently.
Review if the card includes insurance benefits for add-on cardholders. Some premium cards extend travel or purchase insurance to all add-on users.
Consider cards with easy card control features available. You should be able to set spending caps or block add-on cards online quickly.
Ensure the card offers hassle-free redemption of rewards accumulated. All points are typically managed through your primary cardholder account only.
Compare add-on card lounge access and other lifestyle perks carefully. Check if they are shared or pooled between primary and add-on cardholders.
Many people hold incorrect notions about add-on credit card benefits and features. You should understand these misconceptions before applying for add-on cards for the family.
Add-on cards do not always carry the same benefits as your primary card. Some perks like add-on cards, lounge access, or insurance, may be limited to you only.
Not all add-on cards are fee-free for cardholders. Some banks charge joining or annual fees for add-on cards, especially for premium variants.
Rewards and points from add-on cards always pool into your primary account. However, not all cards allow independent redemption by add-on users at all.
Add-on cards do not have a separate credit limit assigned. All spends are deducted from your primary card's total credit limit only.
You remain fully liable for all add on card transactions made. This applies even if the add-on cardholder defaults on payments or overspends.
Disclaimer:
The information on this page, including any “Top” or “Best” lists, is based on data from our Partner institutions and objective parameters such as interest rates, loan amounts, tenure, and other factual criteria. These lists are not exhaustive and do not cover the entire market. We do not claim that featured products are universally the best or suitable for everyone. Details are accurate as of the date shown and may change without notice. Rankings are for informational purposes only and do not constitute financial advice or personal recommendations. They should not be considered endorsements or guarantees of suitability. Bajaj Markets operates as a neutral marketplace and shall not be liable for any loss or damage arising from reliance on this information.
Cards like SBI Card PRIME, IDFC FIRST Bank Wealth Credit Card, and Kotak League Platinum offer various benefits. These include add-on card lounge access, reward points, and fuel benefits for users.
You and add-on users can enjoy pooled rewards and shared lounge access. Consolidated billing is also available, depending on your card's specific terms and conditions.
Yes, add-on credit card spends earn reward points and cashback for users. These rewards are credited to your primary cardholder account for redemption purposes only.
No, add-on cards do not have separate or customised credit limits assigned. They share your primary card's total credit limit for all transactions made.
Most add-on cards have no annual fee charged to cardholders. Some premium cards may charge fees for add-on cards, especially for new issuances.
SBI, IDFC FIRST, and HDFC cards typically allow up to 3 add-on cards. These are available for immediate family members over 18 years of age only.
Consider reward sharing, add-on card lounge access, insurance coverage, and fee structure. Card control features are also important when selecting the best add-on credit card.
The primary cardholder is responsible for paying the outstanding amount on the add-on card. Transactions made through the add-on card are included in the primary card account.
An add-on credit card is linked to the primary cardholder's account. It allows another eligible person to use the available credit limit of the primary card.
The fee for an add-on card varies by issuer and card type. Some issuers may offer add-on cards without an additional fee, while others may charge a fee.
Unpaid credit card dues can remain subject to recovery, interest and applicable charges. The account status and credit information may also be affected based on the issuer's reporting and applicable rules.
Eligibility varies by issuer and credit card. Add-on cards are generally issued to eligible family members or other permitted individuals linked to the primary cardholder's account, subject to the issuer's terms.

Academy by Bajaj Markets
 165542

Unlock the world of credit! From picking the perfect card to savvy loan management, navigate wisely.
 97887
Money Management and Financial Planning covers personal finance basics, setting goals, budgeting...
 28606
Explore the investment cosmos! From beginner's guides to sharp-witted strategies, explore India's treasure trove of options.
 47203
Navigate the tax maze with ease! Uncover Income Tax 101, demystify jargon with Terms for Beginners, and choose between Old or New Regimes.
 18764
Discover essential insights on various types of insurance in India.
 4584
Welcome to Tech in Finance, where we explore the exciting intersection of technology and finance...






 Academy