Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
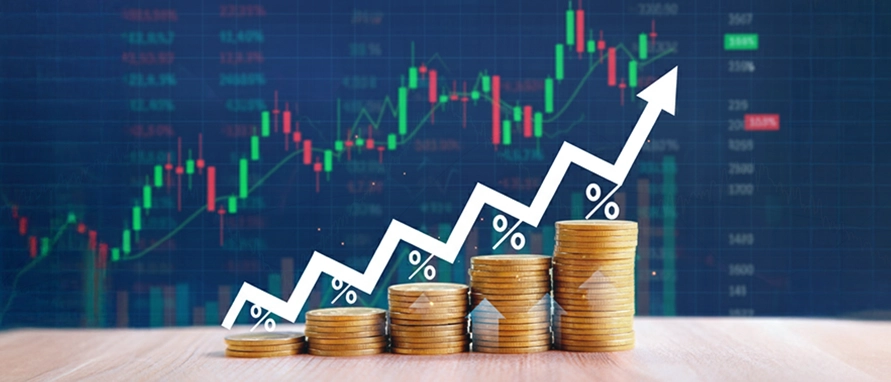
The power of compounding is the process by which your investment earns returns, and those returns, when reinvested, generate additional returns over time.
What is the power of compounding, in simple terms? The power of compounding meaning comes down to this: it is the process where your returns generate additional returns when they are reinvested over time. It is often described as "interest on interest". This means that not only does your initial investment grow, but the returns earned on that investment also start earning. Over time, this can lead to substantial growth, depending on the rate of return, investment duration, reinvestment of returns, and, where applicable, market performance.
For instance, if you invest ₹10,000 and earn 10% annually, in the first year, you will earn ₹1,000. In the second year, you will earn 10% not just on ₹10,000, but on ₹11,000 resulting in earnings of ₹1,100. This cycle continues, and over time, the growth curve becomes steeper.
The standard formula to calculate compound interest is:
A = P × (1 + r/n) ^ (nt)
Where:
A = Final amount (Principal + Interest)
P = Initial investment (principal)
r = Annual interest rate (in decimal)
n = Number of times interest is compounded per year
t = Time in years
If you invest ₹50,000 at an interest rate of 8% compounded annually for 10 years:
A = 50,000 × (1 + 0.08/1) ^ (1×10)
A = 50,000 × (1.08)^10 ≈ ₹1,07,946
Thus, the investment grows to more than double its original amount in 10 years without any additional contribution.
With simple interest, you only earn a return on your original amount, year after year — the amount you earn stays the same each year. With compound interest, you earn a return on your original amount plus all the returns you have already earned, which illustrates the principle of compounding.
Using the same ₹10,000 example at a 10% annual rate:
Simple Interest: You earn ₹1,000 every year, since it is always calculated on the original ₹10,000. After 10 years, you would have ₹20,000.
Compound Interest: You earn ₹1,000 in year one, but ₹1,100 in year two (since it is now calculated on ₹11,000), and the amount you earn keeps growing each year. After 10 years, you would have ₹25,937.
Over time, the compounding effect becomes more pronounced with this growing gap between the two.
Let us look at a power of compounding example to see how this plays out in practice. The following scenarios are an example of power of compounding across a lump sum investment and a recurring one:
Invest ₹10,000 at 10% annual return for 10 years
Future Value = ₹10,000 × (1.10)^10 = ₹25,937
Invest ₹1,000 per month in a mutual fund earning 12% annual return for 15 years
Future Value ≈ ₹5,00,000 (approximate value, depending on assumptions)
This shows that both lump sum and recurring investments can significantly benefit from the power of compounding especially when started early.
Compounding in equity investments occurs when gains or dividends are reinvested, increasing the investment base for potential future returns. Since market returns are not guaranteed, the extent of compounding depends on the investment's performance.
Examples include:
Systematic Investment Plans (SIPs) in mutual funds
Dividend reinvestment in equity stocks
Over time, the compounding effect becomes more pronounced.
Many cumulative fixed deposits calculate and reinvest interest periodically (such as quarterly), although the compounding frequency may vary by financial institution and product.
Principal = ₹1,00,000
Interest Rate = 6.5% p.a.
Duration = 5 years (compounded quarterly)
Future Value = ₹1,38,915
This highlights how even fixed-income instruments benefit from compounding when the interest is allowed to accumulate.
Interest can be added to your investment at different frequencies yearly, quarterly, monthly, or daily. Generally, the more often interest is added, the slightly higher the overall growth, because each addition starts earning its own returns a little sooner.
For example, ₹1,00,000 invested at 6.5% p.a. for 5 years:
Compounded annually: grows to approximately ₹1,37,009
Compounded quarterly: grows to approximately ₹1,38,915
The difference may look small over a few years, but it becomes more noticeable over longer durations or with larger amounts.
Here are some advantages of compounding:
Helps build wealth through consistent investing
Accelerated growth over time
Describes how returns build on themselves as part of long-term wealth planning
Can increase the growth potential of smaller, consistent investments through reinvestment
Reflects how, mathematically, returns compound further the longer money remains invested and reinvested
Mathematically, the longer the time horizon over which returns are reinvested, the larger the compounding effect becomes.
The following factors affect the magnitude of compounding:
Starting early: More years result in more compounding intervals
Longer time horizon: Compounding typically unfolds over long periods
Higher rates of returns: Can lead to larger differences in outcomes over longer periods
Frequent compounding: Quarterly compounding results in more frequent growth periods than annual
Consistent reinvestment: Ongoing reinvestment maintains the compounding cycle
Starting earlier can affect the final accumulated value because compounding has more time to operate.
Compounding is not limited to financial products. The same mathematical principle can also be observed in other situations where growth occurs on an increasing base over time.
For example, population growth often follows a compounding pattern when it increases by a fixed percentage over successive periods. Similarly, certain biological processes, such as the growth of plants or microorganisms, can exhibit comparable behaviour under suitable conditions, with growth occurring on an expanding base.
These examples demonstrate the underlying concept of compounding—where growth is calculated on previously accumulated growth—without referring to any specific financial product.
Compound interest allows returns to grow faster over time compared to simple interest.
| Advantage | Explanation |
|---|---|
Exponential Returns |
Returns grow at a faster rate over time than simple interest |
Predictability |
Certain fixed-income products, such as cumulative fixed deposits, use compound interest calculations based on their applicable terms |
Commonly used in long-term savings products |
Long-term investments like EPF, PPF, NPS use compound interest to build corpus |
Reinvested Growth |
Allows reinvested returns to contribute to future growth |
Compounding is not unique to any one product. The same mathematical principle applies to FDs, mutual funds, PPF, and even everyday examples outside of finance; it is a general concept, not a feature exclusive to any single investment type.
Missing early years cannot simply be made up later without a much higher rate. Since compounding relies on time to build on itself, a shorter remaining time horizon generally needs a proportionally higher rate of return to reach the same end value; it is not something that can be easily offset.
Compounding describes how returns generate further returns when reinvested over time, causing growth to accelerate rather than stay constant. The factors that influence how much of an effect this has include the length of time invested, the rate of return, and how frequently interest or returns are compounded. Actual outcomes vary depending on the specific product, prevailing market conditions, and how consistently returns are reinvested.
It means your money can grow faster over time because you earn returns not just on what you originally invested, but also on the returns you have already earned.
If you invest ₹10,000 at a 10% annual return for 10 years, your investment grows to approximately ₹25,937 because each year's return is calculated on a progressively larger amount, not just the original ₹10,000.
In the stock market, compounding happens when returns like dividends or capital gains are reinvested instead of withdrawn, so future growth is calculated on a larger base each time.
Simple interest is calculated only on your original amount. Compound interest is calculated on your original amount plus any returns already earned, which is why it grows faster over time.







 Academy