Our Products
 Loans
 Cards
 Insurance
 Investment
 Stock Market
 Electronics Mall
 CIBIL Score
 Knowledge Centre
 Calculators
Our Services

 Do not call
 En
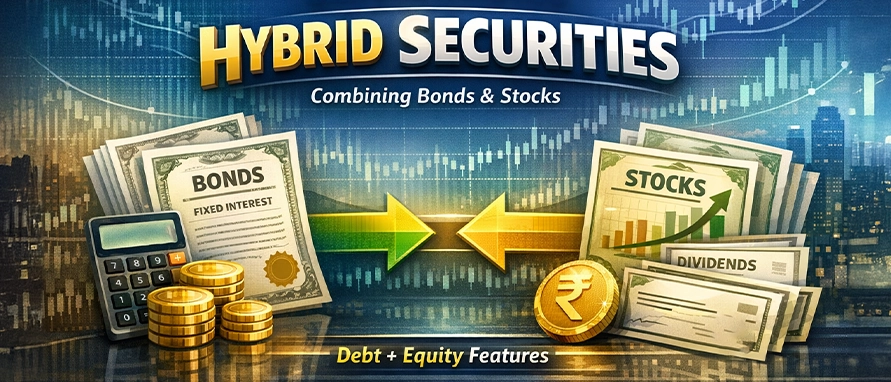
Learn about hybrid securities, their features, types, examples, advantages and limitations.
Hybrid securities combine certain features of both debt and equity, depending on their structure. These financial instruments may include features such as interest or dividend payments, conversion into equity shares, or returns linked to an underlying asset. Common examples include convertible bonds and preference shares, while hybrid mutual funds are investment schemes that combine exposure to equity and debt.
A hybrid security is a financial instrument that combines certain features of both debt and equity. Depending on its structure, it may provide features associated with debt, such as interest or dividend payments, along with equity-related features, such as conversion into shares or returns linked to an underlying asset.
Hybrid securities can be structured in various forms, including convertible bonds, convertible preference shares, and certain preference securities. Convertible bonds are debt instruments that may be converted into company shares according to specified terms. Preference securities may provide preferential rights regarding dividends or repayment of capital, subject to the terms of the issue.
In short, hybrid securities combine characteristics of debt and equity, with their features, rights, and risks depending on the specific type and terms of the instrument
Hybrid securities may have several features associated with both debt and equity instruments, depending on their structure:
Some hybrid securities provide income through interest or dividend payments. The frequency and nature of such payments depend on the terms of the instrument.
Certain hybrid securities, particularly convertible instruments, may provide exposure to changes in the value of the underlying equity, depending on market conditions.
Some hybrid securities, such as convertible bonds, may be converted into equity shares according to predetermined terms and conditions.
In the event of liquidation, the payment priority of a hybrid security depends on its type and terms. Preference securities generally rank ahead of equity shareholders but may rank below debt holders.
The income or returns from hybrid securities can vary depending on their structure, underlying assets, market conditions, and the terms of the instrument.
Common forms of hybrid securities include instruments that combine characteristics of debt and equity:
These are debt instruments that can be converted into a predetermined number of shares of the issuing company according to specified terms. They may provide interest payments along with a conversion feature linked to the company's equity.
These preference shares provide specified dividend rights and may be converted into equity shares according to predetermined terms. Their rights and conversion conditions depend on the terms of the issue.
Hybrid mutual funds are mutual fund schemes that invest in a combination of equity and debt instruments. They are distinct from individual hybrid securities and are classified into different categories based on their asset allocation and investment mandate.
Structured notes are debt instruments whose returns may be linked to the performance of an underlying asset, such as a security, index or other reference variable. Their terms may also include features such as embedded options.
Preference securities have characteristics associated with both debt and equity. They generally provide preferential rights over equity shares with respect to dividends and repayment of capital, subject to the terms of the issue.
Since hybrid securities combine characteristics of debt and equity, they can be compared with shares and bonds across several aspects:
| Aspect | Hybrid Securities | Shares (Equity) | Bonds (Debt) |
|---|---|---|---|
Income |
May provide interest or dividends, depending on the instrument's terms |
Dividends, if declared; not guaranteed |
Interest payments generally specified in the terms of the bond |
Ownership |
May provide equity ownership if the instrument is convertible |
Represents direct ownership in the company |
Represents a debt obligation to the issuer |
Priority in Liquidation |
Depends on the type of security; may rank above common equity but below debt |
Generally has the lowest priority among these three |
Generally ranks ahead of equity holders |
Capital Appreciation |
May occur depending on the structure and market value of the instrument |
Direct exposures to change in share price |
Market value may change before maturity, while principal and interest terms are generally specified |
Risk Level |
Varies according to the instrument's structure, issuer and terms |
Exposed to market and company-specific risks |
Subject to credit, interest-rate and liquidity risks |
Hybrid securities may have several characteristics associated with both debt and equity instruments, depending on their structure:
Certain hybrid securities combine debt- and equity-related features within a single instrument, providing exposure to characteristics of more than one asset class.
Some hybrid securities provide interest or dividend payments and may also offer exposure to changes in the value of equity, depending on their terms.
Certain hybrid securities, such as convertible bonds, provide for conversion into equity shares according to specified terms, combining debt-related features with an equity conversion feature.
Hybrid securities can be structured with different combinations of interest, dividends, conversion rights, repayment terms, or returns linked to an underlying asset.
Hybrid securities may also involve certain limitations and risks that vary depending on their structure and terms:
The combination of debt- and equity-related features can make some hybrid securities more complex to understand, particularly when they include conversion rights or returns linked to underlying assets.
Convertible hybrid securities are subject to the terms of conversion and changes in the market value of the underlying equity. The value of the security may be affected by movements in the underlying shares.
The income or returns from certain hybrid securities may vary depending on their structure, underlying assets, market conditions, or other specified factors.
Hybrid securities issued by companies or other entities may carry credit risk, meaning the issuer may fail to meet its payment obligations according to the terms of the instrument.
Tax treatment for hybrid securities in India depends on the specific instrument, its structure, and the applicable provisions of the Income-tax Act:
Convertible Bonds: Interest received on convertible bonds is generally taxable as income under the applicable provisions. Conversion of bonds or debentures into shares of the same company is generally not treated as a transfer for capital gains purposes. Capital gains may arise when the shares received on conversion are subsequently transferred.
Preferred Stock/Securities: Dividends received on preference shares are generally taxable in the hands of the recipient under the applicable provisions of the Income-tax Act. The tax treatment may vary based on the nature of the instrument and the recipient.
Hybrid Mutual Funds: Tax treatment depends on the fund's investment composition and the applicable tax provisions. From 1 April 2026, a mutual fund investing more than 65% of its total proceeds in debt and money market instruments, subject to the specified conditions, falls within the definition of a Specified Mutual Fund under Section 50AA.
Structured Notes: The tax treatment depends on the structure of the instrument. Market Linked Debentures covered by Section 50AA are treated as short-term capital assets, irrespective of the holding period. The section also applies to specified mutual funds and certain unlisted bonds or debentures covered by its provisions.
Given the differences in tax treatment across hybrid instruments, the applicable tax provisions should be checked based on the specific security, transaction, and prevailing tax rules.
Hybrid securities combine characteristics of debt and equity, depending on the structure of the instrument. They may include features such as interest or dividend payments, conversion into equity shares, or returns linked to an underlying asset. Understanding the type of hybrid security, its terms, payment structure, conversion provisions, and associated risks helps explain how these instruments differ from traditional debt and equity securities.
A hybrid security is a financial instrument that combines certain characteristics of debt and equity. Depending on its structure, it may provide features such as interest or dividend payments, conversion into equity shares, or returns linked to an underlying asset.
Examples of hybrid instruments include convertible bonds, convertible preference shares and certain preference securities. Hybrid mutual funds are investment schemes that invest across asset classes such as equity and debt and are therefore distinct from individual hybrid securities.
Hybrid securities may combine debt- and equity-related characteristics, depending on their structure. Ordinary equity shares represent ownership in a company and do not provide a contractual entitlement to a fixed return. Certain hybrid securities may provide interest or dividend features and may also include conversion rights.
Some hybrid securities have debt-like features, such as interest payments or specified repayment terms. Their priority in liquidation depends on the type and terms of the instrument. Convertible securities may also provide for conversion into equity shares.
Hybrid securities combine characteristics associated with debt and equity. The specific rights and obligations depend on the instrument. For example, a convertible bond may carry interest payments and also provide for conversion into equity shares under specified terms.
Hybrid securities are called “hybrid” because they combine characteristics associated with more than one type of financial instrument, typically debt and equity.






 Academy